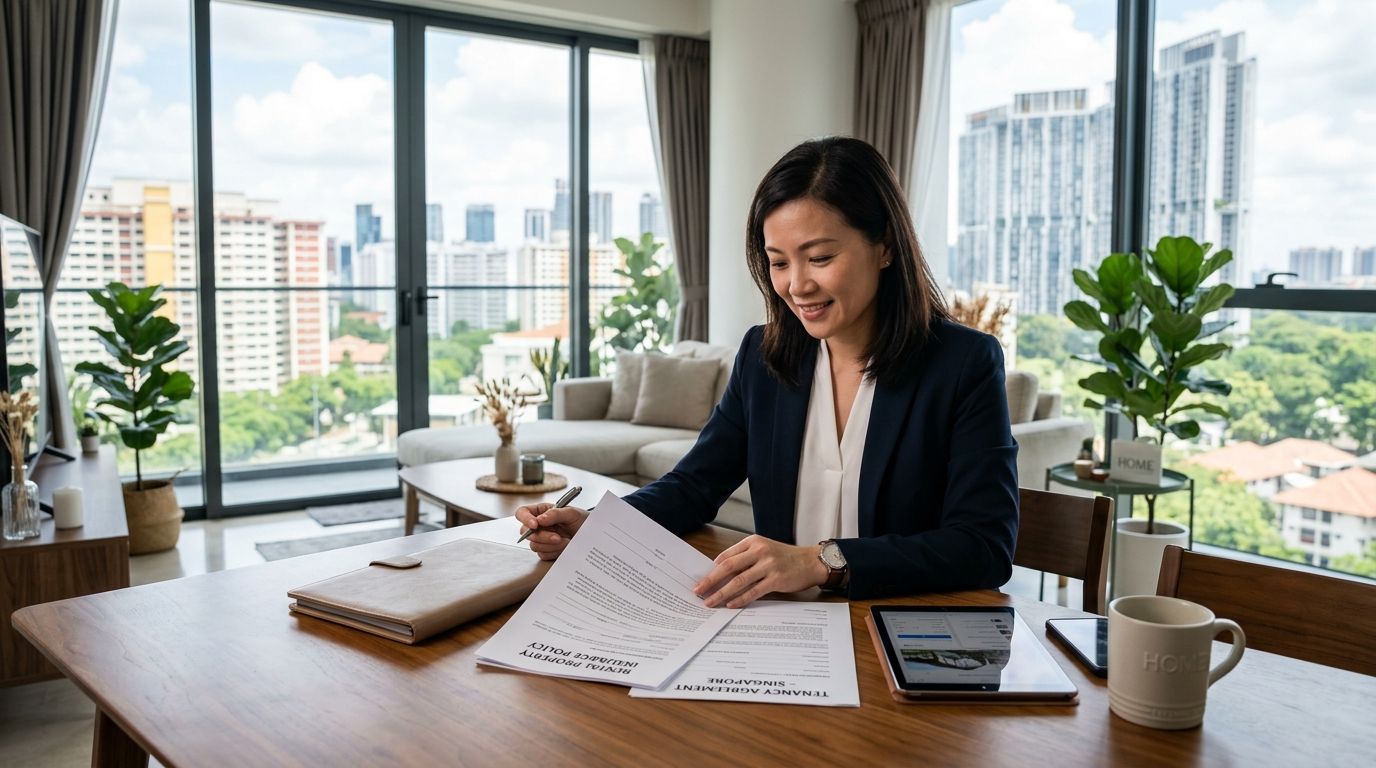
Insuring a rental property in Singapore comes down to layering three things: fire insurance, a landlord contents and liability policy, and loss-of-rent cover — and knowing which one is compulsory and which one is just smart. I walk landlords through this gap every time a unit changes tenants, and it's almost always the loss-of-rent piece that gets skipped.
You insure a rental property in Singapore by combining compulsory fire insurance — through the HDB Fire Insurance Scheme if the flat was bought with an HDB loan, or through the MCST's master policy for condo common property — with a separate landlord policy covering your unit's own fittings, contents and liability. Singapore law does not force private landlords to buy anything beyond the HDB scheme, but skipping cover leaves you exposed to the full replacement cost after a tenant's kitchen fire or a burst washing machine hose. The gap most landlords miss isn't fire damage — it's loss-of-rent: a standard fire policy pays to fix the unit, not to replace the rent you lose while it sits empty for repairs.
- HDB Fire Insurance Scheme is compulsory only when the flat carries an HDB loan — private condo owners have no equivalent legal requirement in 2026.
- An MCST master policy covers the building shell and common property, never your unit's fittings, appliances or contents.
- Landlord insurance (fittings, contents, public liability) is the policy that actually protects your rental income in Singapore.
- Loss-of-rent cover is the piece most landlords forget when they insure a rental property in Singapore.
Why this matters
A rental unit in Singapore sits in someone else's hands for 12 to 24 months at a time under a standard tenancy agreement. You control none of the day-to-day wear, and the property agent service for landlords I run exists precisely because absentee owners need someone checking the unit, not just collecting rent.
Insurance is the part landlords treat as an afterthought until a tenant floods the bathroom or a stove fire scorches a rented condo's kitchen. By 2026, most MCSTs across Singapore's condo developments carry master fire policies that cover the building envelope and common areas — but that policy stops at your unit's front door. Everything inside, from the built-in wardrobes to the aircon compressor, is your liability unless you've separately insured it.
How do I insure a rental property in Singapore as a landlord?
The coverage stack for a Singapore rental property has five layers, and not every landlord needs all five.
| Coverage type | What it protects | Compulsory? | Best for |
|---|---|---|---|
| HDB Fire Insurance Scheme | Structural fire damage to an HDB flat | Yes, if bought with an HDB loan | HDB flat owners with a loan |
| MCST master fire policy | Building shell, common property | Yes, bundled into condo maintenance fees | Condo unit owners (covers building only) |
| Landlord contents/fittings insurance | Your own fittings, appliances, renovations | No | Any landlord letting a furnished or part-furnished unit |
| Public liability insurance | Injury or third-party property damage claims | No | Landlords worried about tenant lawsuits |
| Loss-of-rent insurance | Rental income while the unit is uninhabitable | No | Landlords relying on rental yield to cover a mortgage |
The first two rows are structural — they exist whether you buy anything or not. The bottom three are the ones you actively choose, and they're the ones that decide whether an incident costs you a few days of admin or a few months of lost income.
Fire insurance: compulsory only in specific cases
Fire insurance is mandatory in Singapore only for HDB flats purchased with an HDB housing loan, under the HDB Fire Insurance Scheme. It covers structural damage to the flat itself — the walls, built-in fixtures the flat came with, and the doors and windows — from fire.
It does not cover your furniture, your tenant's belongings, or any renovation you added after purchase. If you're letting an HDB flat, check the HDB rental guide for expats alongside your insurance renewal so the tenancy terms and the coverage gap are both accounted for.
MCST master policy: covers the building, not your unit
Every condo's Management Corporation Strata Title (MCST) carries a master insurance policy funded through maintenance fees. It insures the building structure and common property — lobbies, lifts, the pool, the facade — against fire and structural risks.
What it never covers: your unit's interior fittings, your air-conditioning units, your renovation, or anything your tenant owns. Landlords who assume the MCST has them covered are the ones who end up paying out of pocket after a unit-level incident in 2026.
Landlord insurance: covers your fittings and contents
This is the policy you actually buy as a landlord — it insures the items you own inside the unit: built-in cabinetry, air-conditioning, kitchen appliances, and any furniture you supply. If you furnish a rental condo for tenants in Singapore, the value of that furnishing is exactly what a contents policy is designed to protect.
Most general insurers in Singapore sell this as a standalone "landlord" or "home" policy, distinct from the tenant's own contents cover for their personal belongings.
Public liability insurance: protects you if someone gets hurt
Public liability cover pays out if a tenant, their visitor, or a contractor is injured on your property and holds you liable — a loose railing, a slippery floor, faulty wiring. It's the layer most landlords never think about until a claim letter arrives.
A well-drafted tenancy agreement in Singapore allocates maintenance responsibility clearly between landlord and tenant, and that clarity is what determines whether a liability claim even reaches your insurer.
Loss-of-rent insurance: pays you while the unit is unfit to live in
If a fire, flood, or major repair makes the unit uninhabitable, loss-of-rent cover replaces the rental income you'd otherwise lose during repairs. This is the layer that protects your actual return, not just your asset.
For landlords who calculated their rental yield against a mortgage, a two- or three-month vacancy for repairs without loss-of-rent cover can wipe out a full year's net return.
“A standard fire policy pays to fix the unit, not to replace the rent you lose while it sits empty for repairs.”
Why insurance needs vary between landlords
- Property type — HDB flats have a compulsory scheme; condos and landed homes don't.
- Furnishing level — a fully furnished unit carries far more insurable contents value than a bare unit.
- Tenant profile — corporate leases and diplomatic tenancies often carry their own liability clauses that shift some risk back to the tenant.
- MCST policy scope — some MCSTs carry broader master policies than others; check the by-laws before assuming coverage.
- Mortgage terms — some banks require proof of fire insurance as a loan condition, independent of the HDB scheme.
- Renovation value — a heavily renovated unit needs contents cover sized to the renovation cost, not the original fit-out.
Renting out a condo in Singapore?
I help landlords manage tenancy, compliance and insurance gaps end to end.
Is fire insurance compulsory for private condo landlords in Singapore?
No — fire insurance is compulsory in 2026 only for HDB flats bought with an HDB loan; private condo and landed property owners have no equivalent legal mandate. The MCST's master policy covers the building's common property regardless, but that's a building-level requirement, not a personal one.
Does the condo's MCST insurance cover my tenant's belongings?
No — the MCST master policy never extends to a tenant's personal belongings or a landlord's fittings inside the unit. Tenants and landlords each need their own separate contents cover for anything inside the four walls.
What happens if a tenant causes damage beyond the security deposit?
The security deposit under a typical Singapore tenancy agreement is usually capped at one to two months' rent, and damage beyond that amount becomes a civil claim unless a liability or contents policy covers it. This is exactly why the liability layer matters more as a unit's renovation value rises.
FAQ
Do I need insurance to rent out my condo in Singapore?
No law forces it, but landlord contents and liability insurance is standard practice for anyone letting a condo in Singapore in 2026 because the MCST master policy stops at the building shell.
Is HDB Fire Insurance the same as landlord insurance?
No, the HDB Fire Insurance Scheme only covers structural fire damage on flats bought with an HDB loan — it doesn't cover contents, fittings, or loss of rent, which is what landlord insurance is for.
Who pays for landlord insurance, the landlord or the tenant?
The landlord pays for landlord insurance covering their own fittings and contents; tenants are responsible for insuring their own personal belongings separately.
Does loss-of-rent insurance cover a tenant who simply stops paying rent?
No, loss-of-rent cover only pays out when the unit becomes physically uninhabitable due to an insured event like fire or flood, not for tenant default or non-payment.
Can I insure a rental property in Singapore if I live overseas?
Yes, overseas landlords can buy Singapore landlord insurance remotely through most local insurers, though many rely on a local agent to manage claims and inspections on the ground.
Does public liability insurance cover a tenant's injury inside the unit?
Yes, public liability insurance covers claims when a tenant or visitor is injured due to a hazard the landlord is responsible for maintaining.
Is landlord insurance required to get a home loan in Singapore?
Some banks require proof of fire insurance as a loan condition on top of any HDB or MCST requirement, so check your mortgage terms before assuming the HDB scheme alone satisfies the bank.
One last thing
The insurance question landlords ask me last is usually the one that matters most: what happens between tenancies, when the unit sits vacant during handover. Most landlord policies still apply during a vacant period, but confirm it explicitly with your insurer before you assume a gap in occupancy voids the cover — that single line in the policy wording is where most disputes start.